

Why a Spreadsheet Still Works in 2026
Budgeting apps are convenient, but convenience comes with a tradeoff: when categorization happens automatically, a lot of people stop paying close attention to it. A spreadsheet requires you to enter each transaction yourself, and that small manual step means you're mentally registering every purchase instead of letting software quietly file it away. For people who've tried apps and found themselves ignoring the notifications, a spreadsheet's low-tech friction is often the feature that makes it stick.
Spreadsheets are also fully customizable and free, which matters if you've hit the limits of what a templated budgeting app lets you categorize or if you'd rather not link your bank account to a third-party service.
Setting Up Your Spreadsheet: The Core Structure
Open Google Sheets or Excel and set up four essential columns: Date, Category, Description, and Amount. Keep the structure this simple at first – it's tempting to build something elaborate on day one, but an overly complex system is one of the main reasons people abandon spreadsheet budgeting within the first few weeks.
For categories, start with a short list you can expand later: Housing, Groceries, Transportation, Dining Out, Utilities, Subscriptions, and Miscellaneous covers most people's spending reasonably well as a starting point. You can always split a broad category into more specific ones once you notice it's where most of your money is actually going.
Add a fifth column for Running Balance if you want to see your account trending in real time as you log entries, though this is optional and some people find it easier to check their actual bank balance separately rather than trying to keep two numbers in sync manually.
Logging Transactions Without It Becoming a Chore
The habit that makes or breaks a spreadsheet budget is consistency, not complexity. Set a specific, low-effort routine – logging transactions once a day, ideally at the same time, like right before bed – rather than trying to remember every purchase from memory a week later. Waiting too long between entries is the single most common reason people fall behind and eventually give up.
Keep your phone's browser bookmarked to your spreadsheet, or use the Google Sheets or Excel mobile app, so you can log a purchase within a minute or two of making it rather than needing to sit down at a computer later. The lower the friction to log an entry, the more likely the habit actually sticks past the first few weeks.
Turning Raw Entries Into Useful Insight
Once you have a few weeks of data, use a simple SUMIF formula to total spending by category: =SUMIF(B:B,"Groceries",D:D) will add up every entry where the Category column says "Groceries," assuming your amounts are in column D. Repeating this for each category gives you a monthly breakdown without needing to manually add anything up.
A basic pivot table takes this further, letting you see totals by category and by month side by side without writing individual formulas for each one. Most spreadsheet programs offer built-in pivot table tools under the Insert menu, and once it's set up, it updates automatically as you add new entries.
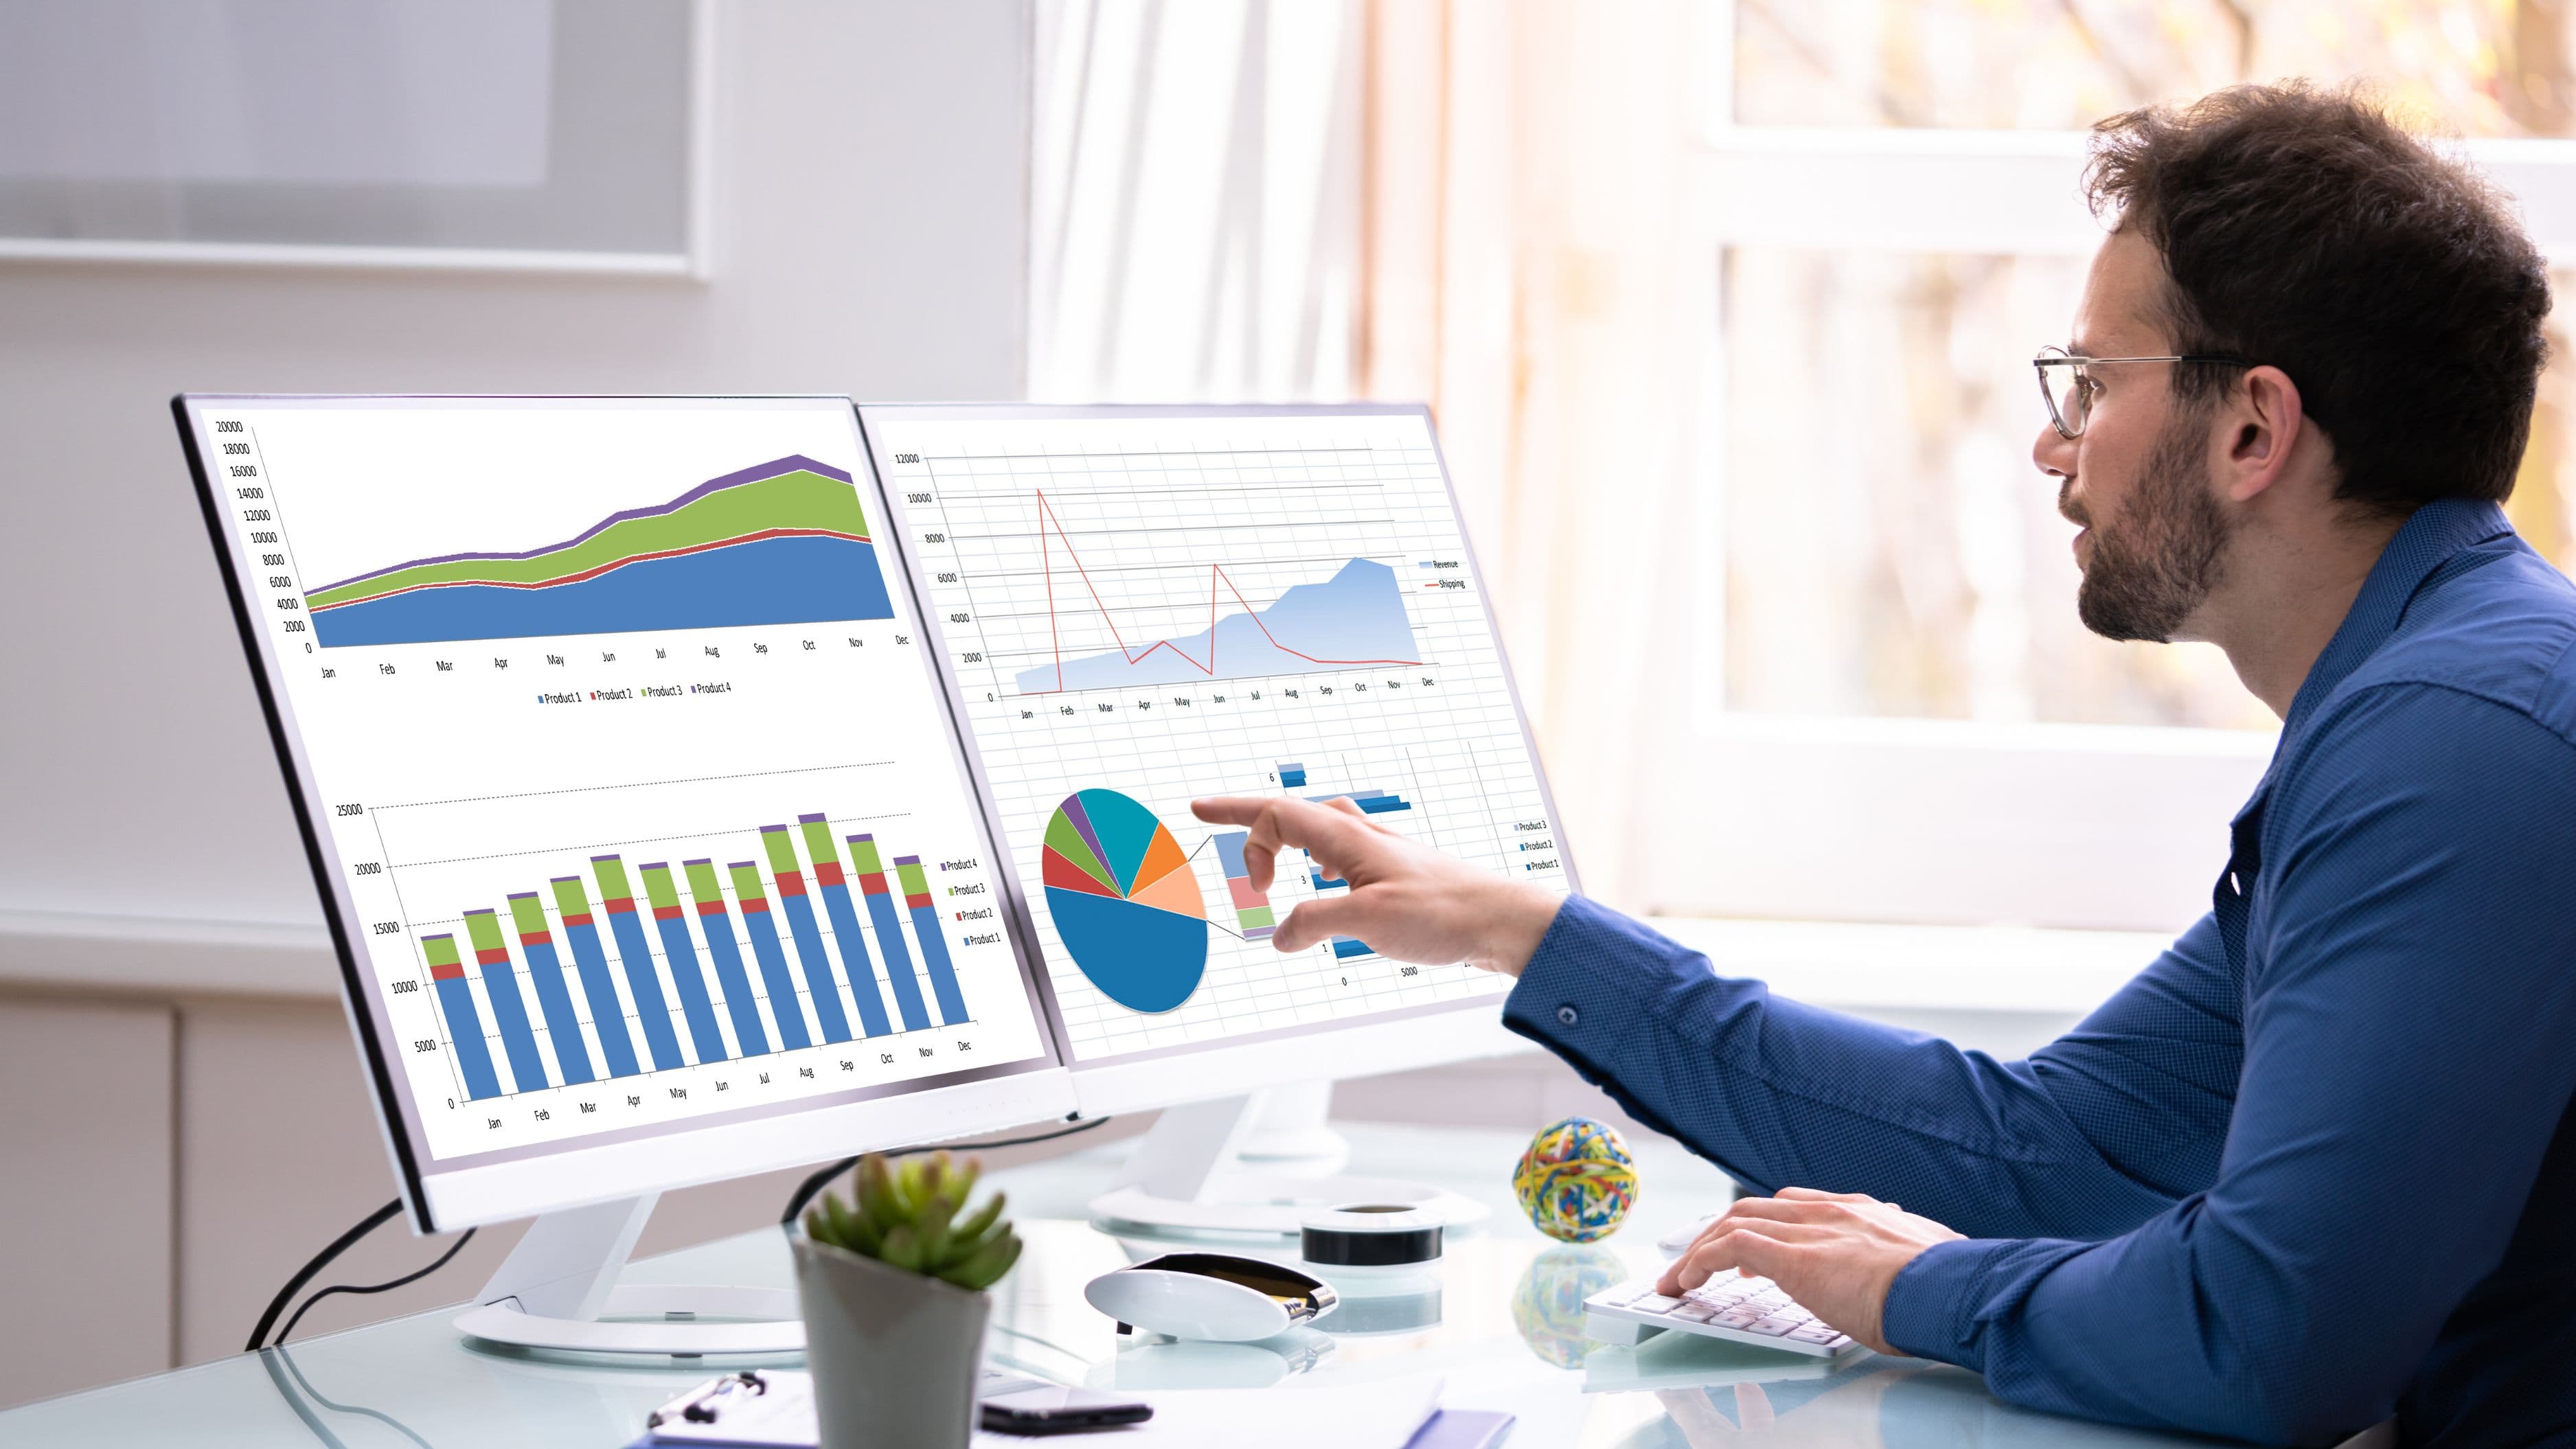
Adding a simple bar chart of your monthly category totals makes patterns visible in a way that a column of numbers doesn't. Seeing that dining out is consistently your third-largest expense category, month after month, tends to land differently than just reading a number.
Realistic Expectations for the First Month
Your first month of spreadsheet tracking will likely feel more tedious than any month after it, since you're still building the habit and figuring out which categories actually fit your spending. It's common to miss a few small purchases in the first couple of weeks – that's a normal part of the learning curve, not a sign the system isn't working.
Give the process a full month before judging whether it's giving you useful insight. Most people don't see clear spending patterns until they have at least three to four weeks of consistent entries to compare against each other.
Key Takeaways
Start with four simple columns – Date, Category, Description, Amount – and resist adding complexity too early
Log entries daily, ideally right after each purchase, to avoid falling behind and abandoning the habit
Use SUMIF formulas or a pivot table to turn raw entries into category totals without manual math
Give the system a full month before evaluating whether it's working for you
Keep the spreadsheet accessible on your phone to minimize the friction of logging each transaction
What to Avoid
Don't try to build an elaborate, feature-heavy spreadsheet before you've proven to yourself that you'll actually keep logging entries consistently – a simple system you use every day beats a sophisticated one you abandon after two weeks. Also avoid comparing your spending to generic budgeting guidelines too rigidly in the first month; the point of tracking is to understand your actual patterns first, then adjust from an informed starting point rather than an arbitrary rule.
Frequently Asked Questions
Is a spreadsheet better than a budgeting app? Neither is universally better – spreadsheets offer more control and force more manual attention, while apps offer automation. The right choice depends on whether you respond better to hands-on tracking or automatic syncing.
How much time does this take each day? Logging a few transactions typically takes under two minutes once the habit is established, though the first week or two may take slightly longer while you get used to the categories.
Can I use this method for a shared household budget? Yes – Google Sheets in particular makes it easy to share a single spreadsheet with a partner or family member so everyone logs into the same running record.
📚 Sources
Consumer Financial Protection Bureau – "Making a budget" – https://www.consumerfinance.gov/consumer-tools/budgeting/
Google – "Google Sheets Help: SUMIF function" – https://support.google.com/docs/answer/3093583